GA Capital · Vietnam Renewables
Post-FiT TariffMechanics
Fixed FiTs closed in 2021. New EVN PPAs price off cost models with a 12% VND IRR cap, MOIT ceilings, and limited indexation on O&M.
Need to Know
FiTs ended
Fixed USD tariffs closed Oct 2021. Post-2025 PPAs use cost-based pricing capped at 12% VND project IRR and MOIT ceilings.
Capex is frozen
70–85% of tariff revenue (capex recovery) sits in nominal VND with no CPI or FX hedge. O&M indexed ~2.5% p.a.; FX adjustment covers foreign debt principal only.
USD returns compress
Headline 12% VND IRR translates to ~5–9% USD equity after inflation, depreciation, and indexation caps. Execution and capital structure drive where a deal lands.
Executive Summary
Two tariff layers
Retail tariffs track EVN cost recovery for consumers. Generation PPAs for wind and solar use MOIT ceilings plus cost-based models capped at 12% VND IRR.
PPA price sits between model and ceiling
Negotiated tariff must follow the regulated cost stack, deliver ≤12% VND IRR on normative assumptions, and stay under the annual MOIT ceiling for technology and region.
Capex recovery is nominal VND
Wind PPA = FC (capex) + FOMC (O&M). FC is ~70–85% of revenue, fixed without CPI/FX protection. FOMC rises ~2.5% p.a.; FX adjustment covers foreign debt principal only.
12% VND ≠ 12% USD
With 3–4% inflation, 2–3% depreciation, and capped O&M indexation, headline VND IRR converts to ~5–9% USD equity depending on macro and execution.
Deals still close on execution
Below-normative build cost, local debt, stable macro, platform/M&A exit, or USD debt with FX pass-through on principal remain the main levers.
Retail and PPA tariffs move on different rules
Generation pricing is what matters for wind and solar offtake
| Instrument | Mechanism | Relevance | Key features |
|---|---|---|---|
| Retail tariff | EVN adjusts end-user tariffs when its cost base moves materially. This layer does not set renewable PPA prices. | Households and industrial consumers |
|
| Generation / EVN PPA | What EVN pays wind and solar generators under MOIT price ceilings and Circular 12/2025 cost-based rules. | Wind and solar developers on EVN offtake |
|
EVN wind PPA splits fixed capex from indexed O&M
FC dominates revenue; indexation is partial
Fixed Cost (Capex Recovery) (FC)
70-85%Recovers capital expenditure over the contract term
Indexation: None (nominal VND)
- •Fixed in nominal VND once agreed
- •No CPI or FX protection
- •Real value erodes with inflation
- •Largest component of tariff
Fixed O&M (FOMC)
15-30%Fixed operations and maintenance costs
Indexation: Yes, capped at ~2.5% p.a.
- •Adjusted annually by cost/CPI/wage indices
- •Capped at approximately 2.5%/year
- •Partial inflation protection only
- •Smaller share of total tariff
FX Adjustment (Debt) (FX_adj)
VariableCompensates for exchange-rate changes on foreign loan principal
Indexation: Yes
- •Applies to foreign-currency borrowings only
- •Covers loan principal changes, not interest
- •Reduces currency mismatch on debt
- •Equity cash flows remain VND-exposed
• FC = capex recovery, fixed in nominal VND over 20 years.
• FOMC = fixed O&M, indexed annually but capped at ~2.5% p.a.
• FX adjustment applies to foreign-currency debt principal, not the full tariff.
• 70–85% of revenue carries zero inflation or FX protection over the contract term.
12% cap applies to normative costs, not actual build cost
The regulatory model calculates a 12% VND project IRR using reasonable capex, O&M, and financing assumptions. Projects built and operated below those normative costs can exceed 12% in practice. That gap is where value is created under the new regime.
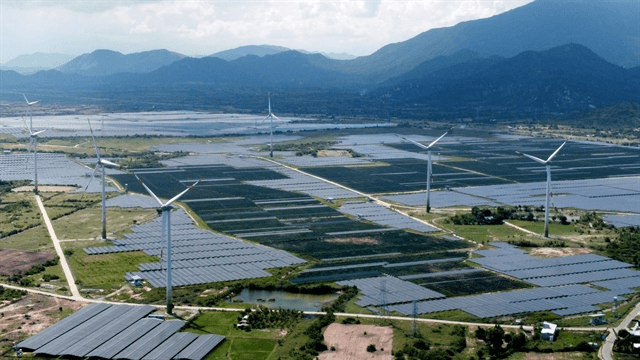
Most tariff revenue sits in nominal VND
O&M and debt FX provide partial protection only
| Component | Indexed? | Detail |
|---|---|---|
| O&M (FOMC) | Partial | Allowed to increase by cost/CPI/wage indices, capped at ~2.5% p.a. |
| FX on foreign loans | Yes | Adjusts for exchange-rate changes on loan principal for USD or other foreign borrowings. |
| Capex recovery (FC) | No | Fixed in nominal VND once agreed; no CPI or FX protection. |
| Full tariff escalator | No | No comprehensive CPI escalator on the entire tariff. |
| Ceiling uplift | No | Existing PPAs do not automatically move up if MOIT raises future ceilings. |
Capex recovery in nominal VND
O&M (~2.5% cap) + FX on debt
• Capex recovery (FC) is the largest share and carries no indexation.
• O&M (FOMC) adjusts by cost/CPI/wage indices but is capped at ~2.5% p.a.
• FX adjustment on foreign debt principal reduces loan-side mismatch; equity remains VND-exposed.
• Higher MOIT ceilings in later years do not automatically lift existing PPAs.
FiT era vs 2025 cost-based regime
Certainty, indexation, and FX protection all narrowed
| Aspect | FiT Era (pre-2021) | Current Regime (2025+) |
|---|---|---|
| Pricing Structure | Fixed US¢/kWh rates set by government | Cost-based model with IRR ≤ 12% cap + MOIT ceiling |
| Tariff Duration | 20 years at fixed rate | 20 years with single fixed or scheduled prices |
| Indexation | None (full USD FiT, no adjustment) | Limited: O&M ~2.5% cap + FX on debt only |
| Revenue Certainty | High (fixed USD tariff) | Moderate (VND exposed, limited indexation) |
| FX Protection | Full (denominated in USD) | Partial (only on foreign debt principal) |
| IRR Framework | Implicit (market set FiT) | Explicit 12% cap on normative costs |
| Price Discovery | Government-set, technology-specific | Negotiated within cost model + ceiling constraints |
Headline 12% VND clears ~5–9% USD equity
Macro assumptions and build cost drive the spread
| Scenario | VND IRR | Inflation | FX Depreciation | Implied USD IRR | Commentary |
|---|---|---|---|---|---|
| Base (Regulatory) | 12.0% | 3.0% | 2.0% | 7.0% | Headline 12% VND project IRR; inflation and FX compress USD equity to ~7%. |
| Optimistic | 12.0% | 2.5% | 1.5% | 8.5% | Lower macro drag lifts USD equity into high single digits. |
| Pessimistic | 12.0% | 4.0% | 3.0% | 5.0% | Higher inflation and depreciation push USD equity toward ~5%. |
| Cost Optimization | 14.5% | 3.0% | 2.0% | 9.5% | Build below normative costs; real project IRR exceeds the 12% regulatory cap. |
• Base: 3% VND inflation, 2% depreciation, O&M capped at 2.5% p.a. → ~7% USD IRR.
• Optimistic: lower inflation (2.5%), lower FX (1.5%) → ~8.5% USD IRR.
• Pessimistic: higher inflation (4%), higher FX (3%) → ~5% USD IRR.
• Cost optimization: build below normative costs → real project IRR ~14.5% → ~9.5% USD IRR.
Five levers that clear 12% VND in practice
Normative cost gap, capital structure, and exit shape the outcome
| Lever | Mechanism | Effect |
|---|---|---|
| Normative vs actual cost | Build and operate below the reasonable costs in the regulator model | Real project IRR can exceed the 12% cap and lift USD equity returns |
| Local debt and capital structure | Cheaper local bank debt and lower sponsor return hurdles | Financing cost reduction improves project economics |
| Conservative macro assumptions | Underwriting assumes higher inflation and FX erosion than base case | Downside protection if macro stays stable |
| Platform / M&A exit | Early entry builds relationships, track record, and pipeline | Platform premium on exit; optionality if policy improves |
| USD debt with FX pass-through | DFI or foreign-bank project finance with PPA FX adjustment on principal | Reduces debt-side currency mismatch; equity stays VND-exposed |
• Regulator uses reasonable costs; below-normative build can lift real IRR above 12%.
• Local sponsors often access cheaper debt and lower return hurdles.
• Platform value from early entry can offset compressed tariff returns on exit.
DPPA adds shape flexibility; ceiling still binds
Corporate offtake does not bypass MOIT price caps
| Dimension | EVN PPA | DPPA | Notes |
|---|---|---|---|
| Price Structure | Cost-based, IRR ≤ 12%, price ≤ MOIT ceiling | Negotiated, but price still ≤ MOIT ceiling | DPPA allows more shape flexibility; ceiling binds both |
| Escalation | Limited: O&M ~2.5% cap + FX on debt | Negotiable within regulatory bounds | DPPA can allow richer escalation subject to offtaker credit |
| Counterparty Risk | EVN (state utility); low default risk | Corporate offtaker; credit-dependent | DPPA requires bankable corporate; EVN is safer but less flexible |
| Volume / Curtailment | EVN dispatch; curtailment risk present | Direct delivery or virtual; terms negotiable | DPPA can specify must-take or curtailment penalties |
| Price Discovery | Regulator-driven (cost model + ceiling) | Market-driven within ceiling constraint | DPPA allows competitive dynamics; ceiling still caps upside |
• Both DPPA and EVN PPA must stay at or below the MOIT ceiling for technology and region.
• DPPA can negotiate escalation terms, but corporate credit and regulatory bounds still constrain economics.
• EVN PPA offers safer counterparty; DPPA requires bankable corporate offtaker.
Policy path from FiT expiry to Circular 12/2025
Decree 57 and Circular 12 define the 2025+ framework
Decree 57/2025/NĐ-CP: Full DPPA Framework
- •Enables direct power purchase agreements between generators and large consumers
- •Price must not exceed MOIT ceiling for tech/region
- •Escalation terms negotiable within regulatory bounds
- •Corporate offtake for creditworthy buyers
Corporate DPPA pathway opens alongside EVN PPAs; ceiling still binds price discovery
Circular 12/2025/TT-BCT: PPA Tariff Mechanism
- •Cost-based tariff calculation mandatory
- •Project IRR capped at 12% (VND) on normative costs
- •O&M indexation capped at ~2.5% p.a.
- •FX adjustment for foreign debt principal only
Fixed FiTs replaced by IRR-capped, cost-based pricing with limited indexation
Decree 80/2024/NĐ-CP: Transitional DPPA
- •Introduced initial DPPA framework
- •Bridge between FiT expiry and new mechanism
- •Set foundation for Decree 57 refinements
Early DPPA adopters (e.g., LEGO Sep 2025) operated under this framework
Decision on Ceiling Prices: Solar & Wind
- •Solar ground: 5.05 US¢/kWh; floating: 6.43 US¢/kWh
- •Onshore wind: 6.77 US¢/kWh; offshore: 7.75 US¢/kWh
- •Applied to transitional projects pending new PPA rules
Lower than legacy FiTs; compressed revenue expectations for 2023-2024 projects
FiTs → ceiling prices → cost-based IRR caps
Headline rates and indexation narrowed at each step
| Period | Mechanism | Solar Range | Wind Range | Notes |
|---|---|---|---|---|
| 2017-2021 | Fixed FiTs | 7.09-9.35 US¢/kWh | 7.80-9.80 US¢/kWh | Fixed USD tariffs; high certainty; FiT windows closed Oct 2021 |
| 2023 (Transitional) | Ceiling Prices | 5.05-6.43 US¢/kWh | 6.77-7.75 US¢/kWh | Lower caps for transitional projects; no indexation |
| 2025+ | Cost-based + IRR Cap | Cost model, IRR ≤ 12% VND, ≤ MOIT ceiling | Cost model, IRR ≤ 12% VND, ≤ MOIT ceiling | Limited indexation (O&M ~2.5%, FX on debt); 20-year term |
• FiT era: fixed USD rates, high certainty; windows closed Oct 2021.
• 2023 transitional ceilings sat below legacy FiTs for bridge projects.
• 2025+ regime: cost-based model with 12% VND IRR cap, MOIT ceiling, limited indexation.
Sources
- Circular 12/2025/TT-BCT: PPA tariff mechanism
- Decree 57/2025/NĐ-CP: DPPA framework
- Decree 80/2024/NĐ-CP: Transitional DPPA
- Decision on ceiling prices (Jan 7, 2023)
- World Bank: Vietnam power sector notes
- IEA: Vietnam country profile
- MOIT annual price ceiling announcements